
Live webinar · Wednesday, October 21 · 12:00 PM ET · 30–45 minutes
A client can lock in 6% a year for five years, guaranteed by the issuing insurer.1 How much more would you need to expect from equities before you'd take market risk with that same money instead?
Starts in
Free for financial professionals. 30–45 minutes, including live Q&A. Zoom link arrives by email.
For financial professional use only. By registering you agree to receive event communications from DMI. Unsubscribe any time.
Can't make the 21st? Book 20 minutes with Declan and bring a live case.
Have a client case right now? You don’t need to wait for October 21.
The question behind the session
No wrong answer. We'll ask the room the same thing live on October 21 and show where advisors land.
A client can lock in 6% for five years. How much extra annual return would you need to expect from equities before you'd tell them to take the market instead?
So you'd need equities to deliver 7.50% a year.
That is the number to hold the recommendation against. On October 21 we put it next to what five-year money actually costs and earns right now, and you decide whether it still looks right.
Most annuity conversations argue about whether the market will go up. This one asks something narrower and harder to dodge: how much is your client being paid to take the risk?
Your answer is your risk premium. Once you've named it, every forecast, spread and rate sheet becomes a yes-or-no test against your own number.
We open the session by polling the room on this exact question.
Lock in an answer and bring it on the 21st.
What the client trades for it
The guarantee is the insurer’s, not the government’s, so carrier strength is part of the recommendation. Surrender charges apply if the client leaves early, and penalty-free liquidity is usually limited to about 10% a year. We cover all three on the 21st.
Agenda
Your hurdle answer, the September curve, and the Fed’s first rate increase since 2023.2
What investors earn for taking credit risk today, and what a contract earns instead.
The $1 million year-one example, then the honest multi-year math, including the tax on the way out.
What comes off the top on each side of the comparison, and what is actually left for the client.
MYGA, corporate bond and Treasury side by side, and what the table does not say.
Your hurdle against five major forecasts, the best case against this thesis, and how to answer without overselling.
Inflation, liquidity, taxes, carrier strength, and giving different dollars different jobs.
Bring a case. Declan stays on if hands are still up.
Who it's for
If you already run a MYGA ladder for every client, you'll hear things you know. If you've never treated a MYGA as a fixed-income decision, this is the session.
You run a fee-based book and have never treated a MYGA as a serious fixed-income substitute. This argues it as a rate-versus-risk decision, with the fee and tax math shown, not a product pitch.
Your clients hold maturing CDs, cash and short corporates, and you need a defensible answer for the next five years of that money.
You already have insurance capability and want a cleaner framework for deciding which dollars belong under contract and which belong in the market.
Your presenter
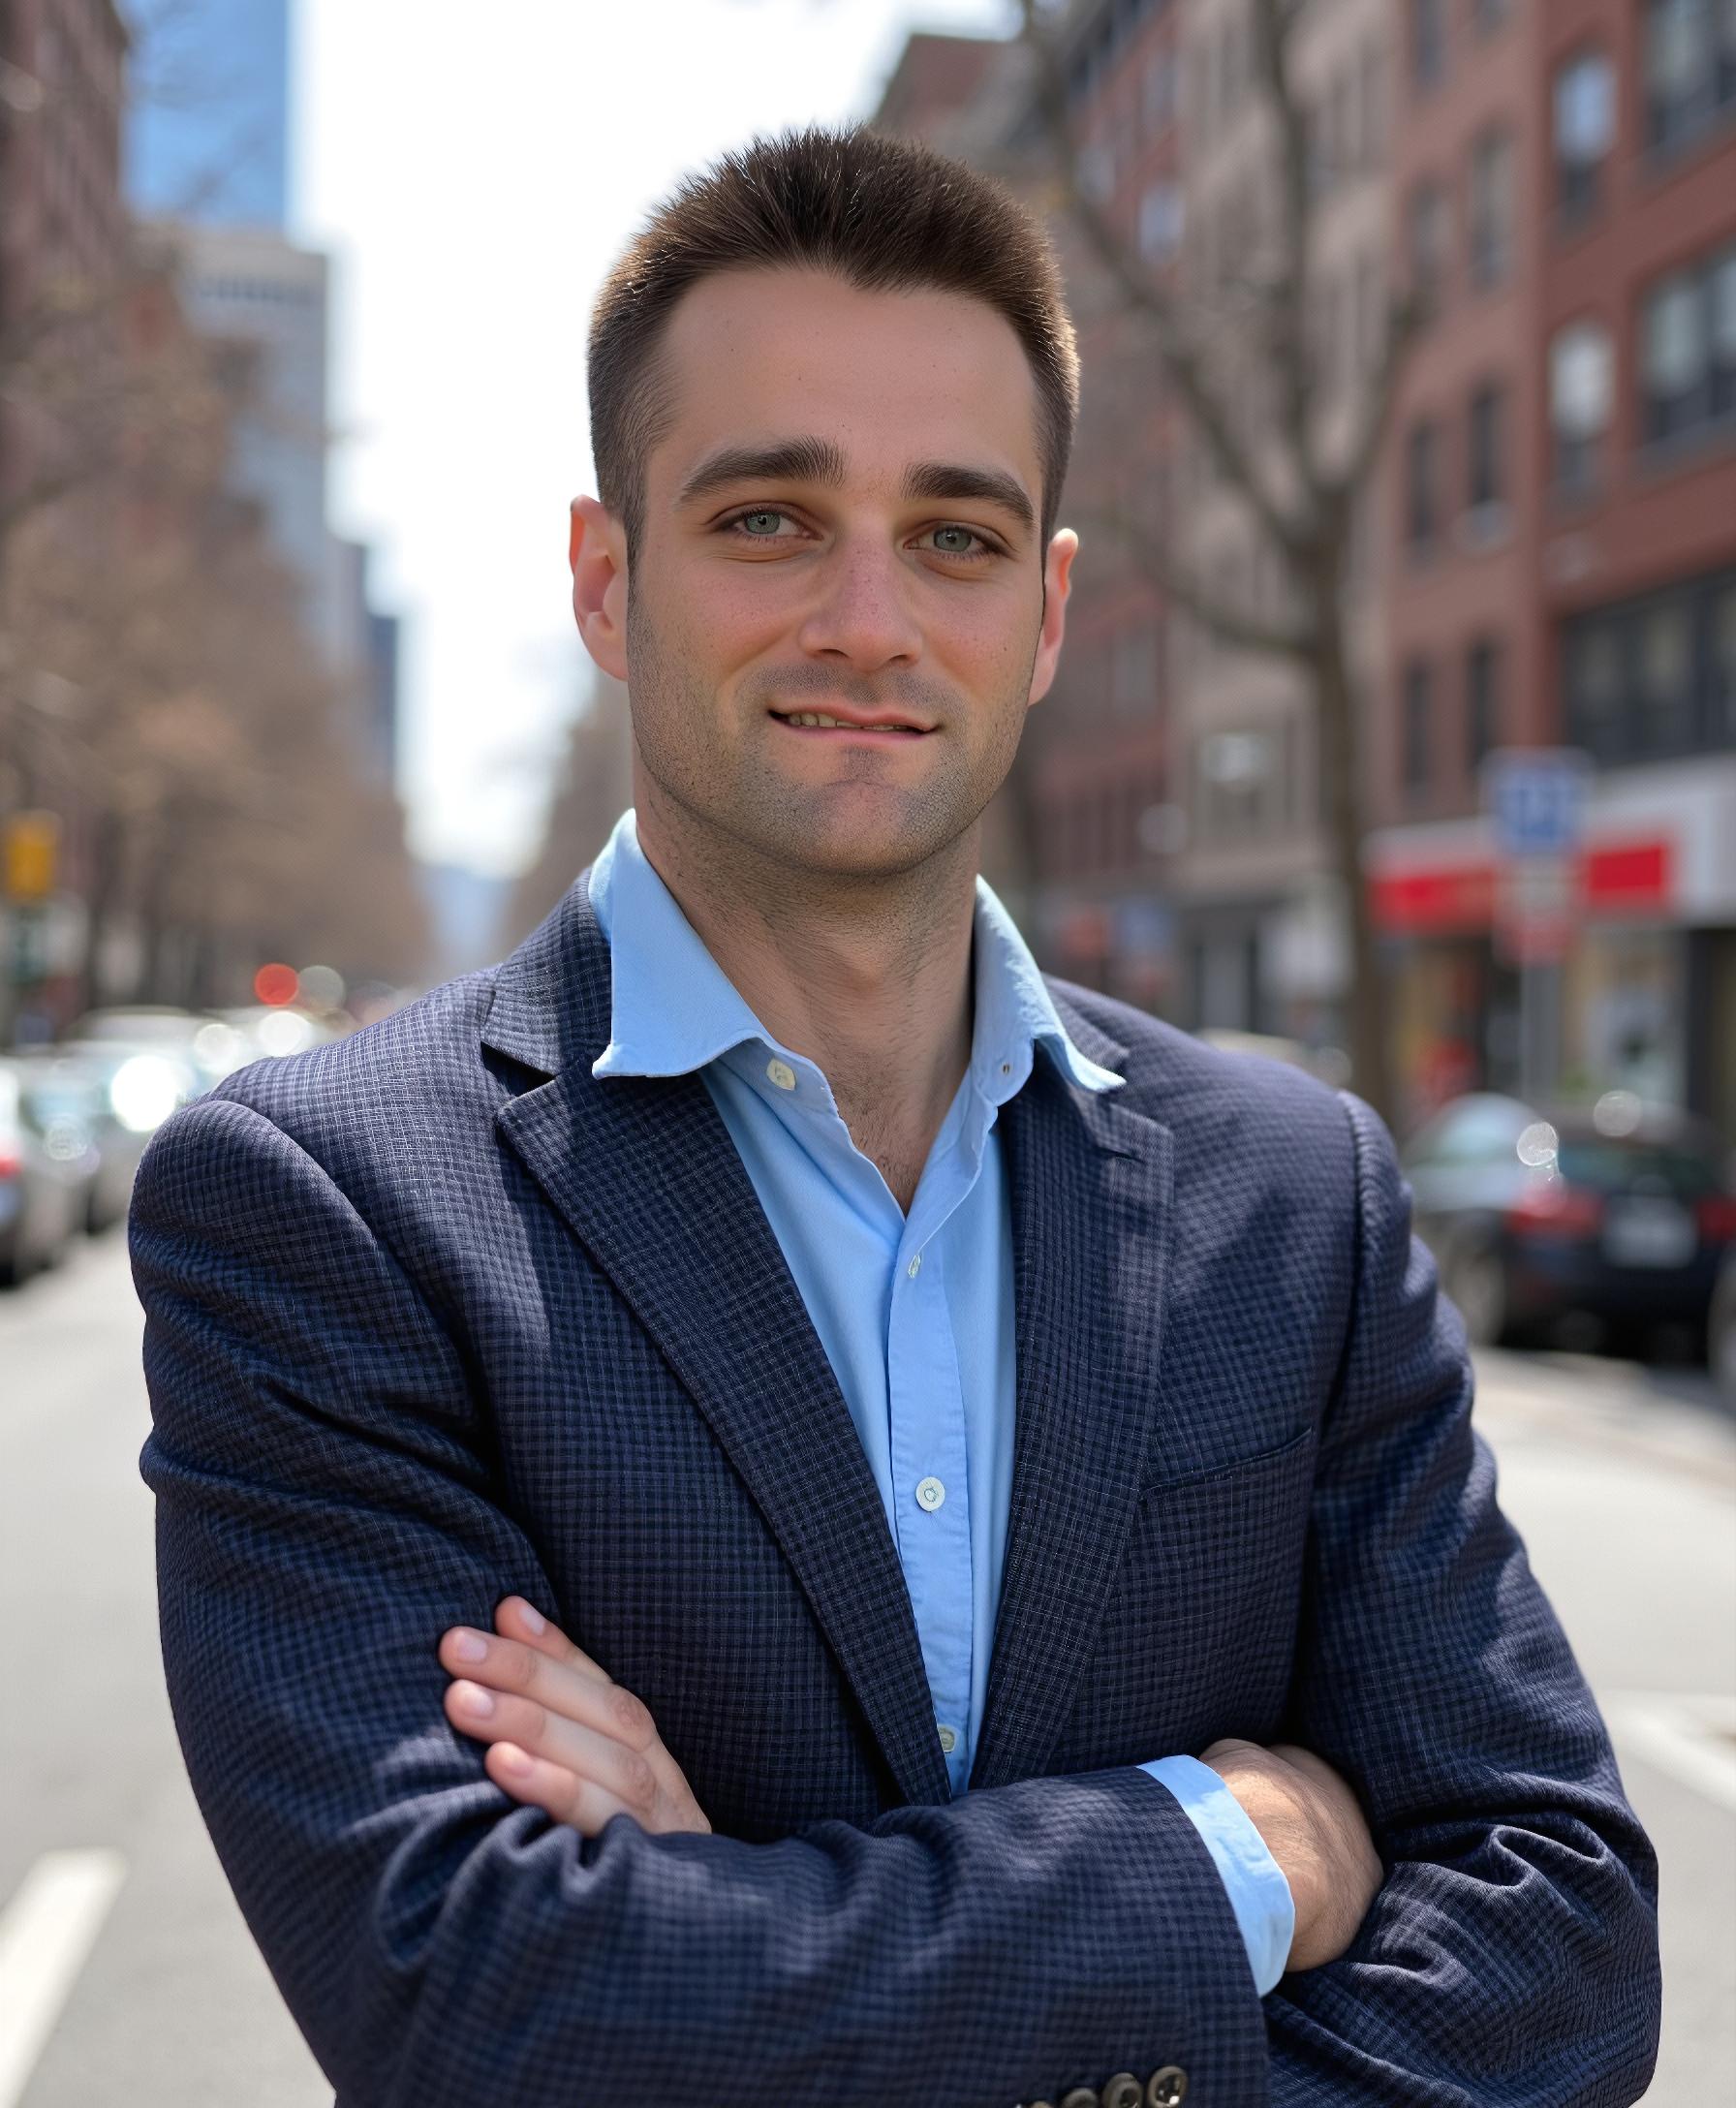
VP Annuities, DMI
Declan works with RIAs, broker-dealer reps and hybrid advisors on where contractual assets belong inside a managed portfolio — product selection, carrier diligence, and the client conversation that gets a case to issue. He runs DMI's MYGA desk, which quotes across 30+ carriers daily, and is a regular presenter for DMI University.
He wrote The 6% Question, the article this session is built on.
October 21 · 12:00 PM ET · 30–45 minutes
Registration is free for financial professionals. Everyone who registers gets the full follow-up package, whether or not you attend live.
Want to see current rates first? Visit the DMI MYGA Store.
Questions
Plan on 30–45 minutes. We keep the material tight and leave the rest for Q&A, so it ends when the questions do. Register either way — the recording goes to everyone.
No. No carrier logos and no rate sheets on screen. It is a pricing argument about what investors are actually paid to take risk with five-year money. If you want to talk products afterwards, that's a separate conversation.
The issuing insurance company. A MYGA is backed by that carrier’s claims-paying ability. It is not FDIC insured and there is no government backstop, so carrier financial strength is part of the recommendation rather than a footnote — we spend time on how to read it. Rates are current as of the session and change daily.1
No. Book time with Declan and bring the case, or check current rates in the DMI MYGA Store.
Register anyway. The recording, deck and client conversation guide go to every registrant the next morning.
No CE credit is offered for this session.
Financial professionals only — RIAs, broker-dealer registered representatives, hybrid advisors and licensed insurance professionals. This session is not for the general public.
Please do. We close with open Q&A, and Declan stays on if there are still questions.
Important disclosure. For financial professional use only. Not for use with the general public. This program and page are educational and illustrative. They are not investment, legal or tax advice and are not a recommendation to buy or sell any product or security. Rates, yields and spreads referenced are as of the dates shown and change daily. Forecasts are estimates, may change, and are not guarantees of future performance. The S&P 500 is an unmanaged index and cannot be invested in directly. Hypothetical illustrations, including the interactive calculator, assume reinvestment at stated rates, use simplified federal tax assumptions, and do not reflect any specific product, account or client situation.
Non-qualified annuity gains are taxed as ordinary income when withdrawn, and withdrawals before age 59½ may be subject to a 10% federal additional tax. MYGA contracts may include surrender charges, market value adjustments and withdrawal restrictions; terms, rates and availability vary by carrier and state. Annuities are issued and backed by insurance companies. Guarantees are subject to the financial strength and claims-paying ability of the issuing insurer, and annuities are not FDIC or SIPC insured or guaranteed by any bank or government agency. Review the issuing insurer’s financial strength ratings (AM Best, S&P, Moody’s or Fitch) before recommending a contract. No continuing education credit is offered for this session.